In this issue:
- AI loses at the ballot box, and why that may help
- Clay and the restructuring of sales data
- The agentic rev ops market map
01 — THE SIGNAL
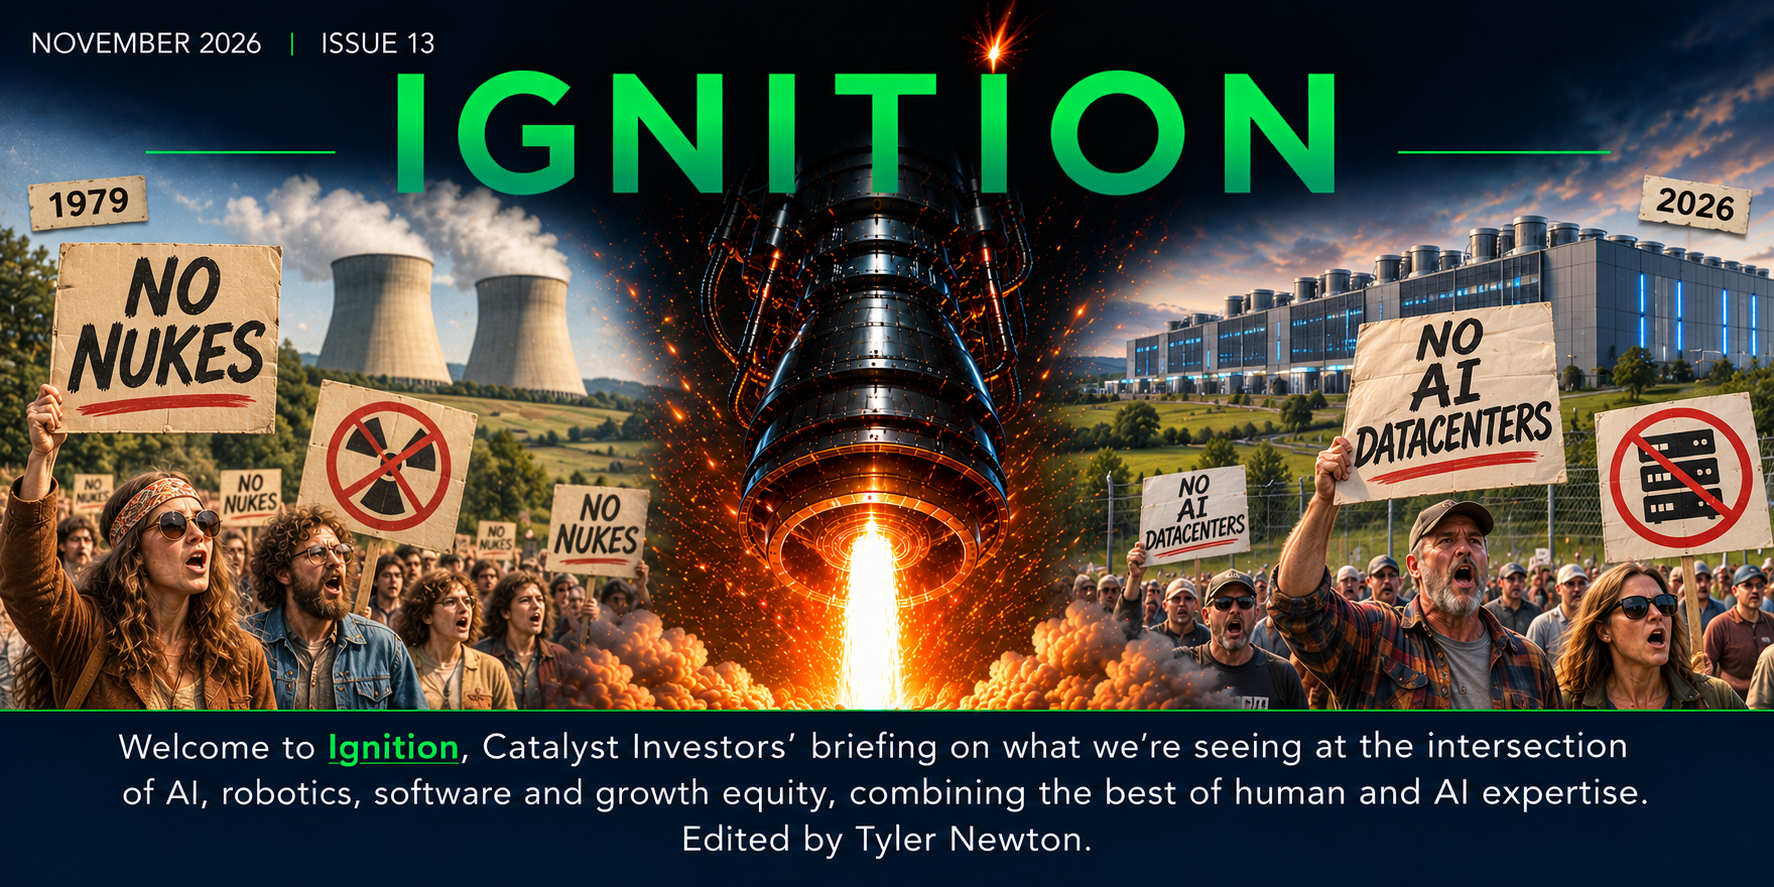
We are all NIMBYs now
AI was on the ballot last Tuesday, and AI lost.
What the Voters Did
Voters faced roughly 40 local ballot measures on data centers across at least ten states. The restrictive side won all but one. Ohio alone had 21. The measures that limited data centers averaged about 75 percent of the vote, which is the more alarming number. Democrats flipped five governorships, among them Texas, Ohio and Georgia, three of the largest data center states in the country, and all three winners campaigned on restricting the buildout. Data Center Watch counts 32 of the 34 winning gubernatorial candidates as supporting tighter regulation and 12 of the 34 as supporting outright bans or moratoriums. That is close to a consensus result.
Why the Public Turned
The industry made this easy. For two years the leading labs told the public that their technology would take its jobs and might end the world and then poured concrete across rural America fast enough to show up in the consumer price index. Electricity prices rose 5.9 percent year over year as of May against 4.2 percent for inflation generally. JPMorgan estimates that some memory chip prices will have risen as much as 400 percent between 2024 and the end of this year, which is why Apple raised laptop prices roughly 15 to 25 percent in June and Microsoft put another hundred dollars on the Xbox. The buildout did not arrive only as a windowless, humming hulk outside a small town in Ohio. It was perceived to arrive in the power bill and at the checkout counter. NIMBY is a slur right up until the thing in your backyard is the reason your electricity costs more.
The Slowdown Arrives in 2028
Little changes before then. SemiAnalysis estimates that about 75 percent of the 33.8 gigawatts due to come online in 2027 across 20 major states has already broken ground, and permitted projects are expected to proceed. Texas governor-elect Hinojosa has acknowledged that existing approvals cover essentially all of Texas’s 2027 pipeline. The exposure sits in 2028, where much of the expected 62.2 gigawatts has not started. JPMorgan puts roughly 37 gigawatts of that year at permitting risk, and UBS puts about 30 percent of the year’s additions at risk of delay.
A two-year fuse is long enough to be useful. The hyperscalers are already under investor pressure to show returns on a capex program whose yield does not presently justify its pace, and a brake applied from outside is considerably cheaper than one applied by the market. They can now moderate spending and point at several governors while doing it.
What the Industry Does Next
Three adjustments follow.
- Model companies will focus on training and inference efficiency and will quietly trim forward compute commitments. Most of them need to do these things anyway.
- Developers will sweeten the terms, which is already happening: $20 million into a community development fund in Lancaster, a $15 million animal shelter in Ellis County, Texas, and a proposal in Hazle Township, Pennsylvania to hand $10,000 to every household, which residents promptly called a bribe. OpenAI published a framework last Thursday promising financial assurances so other ratepayers are protected if a project slips. This trend will hurt the return on investment of large data center projects.
- As a result, datacenter footprints will shrink, with more compute pushed toward smaller sites nearer to where it is consumed.
The Catalyst Take: Toward “Distributed Compute”
Data centers are being treated like nuclear power plants. Both are enormous installations dropped into rural settings where their scale is out of place. Both draw opposition less from what they are than from what they are understood to produce. Nuclear never solved that problem by building bigger reactors or by explaining them more patiently. It is currently trying to solve it by building smaller ones. A modular reactor is tolerable in places where a gigawatt plant never was.
The same logic applies to datacenters. A hyperscale campus concentrates every cost in one county and ships the benefit out of state, which is difficult to defend at a town meeting and nearly impossible to defend on a ballot. Smaller sites and more distributed compute spread the load, lower the local stakes, and end the argument the industry has spent two years losing. The industry spent that time insisting the public should trust it with something world-altering. The public declined, and in declining may have handed it the discipline it could not impose on itself.
02 — OPERATOR’S EDGE
Clay
Clay raised $115 million in September at a reported $7.1 billion, roughly 36 times its rumored run rate revenue of $200 million (up from $100 million at year end 2025). Clay reportedly has around 17,000 customers. While the price and the revenue caught our attention, we are more intrigued by the product and how it fits into our Agent-Headless System of Record thesis.
What Clay Does
Clay is a list-building tool for outbound sales, bought by rev ops and demand generation teams at B2B companies, by the agencies that run outbound on their behalf, and increasingly by a dedicated GTM engineer sitting between sales and marketing. The job it does is narrow. Take a definition of a good customer, find every company and person who fits it, verify who they are and what they are doing right now, and hand a rep a current list with the research already attached. That used to be three vendors and a week of somebody’s time.
Clay is a spreadsheet that queries the internet. Rows are companies or people. Columns are enrichments. Its core mechanic is the waterfall: rather than buying one vendor’s coverage, you rank 150 providers and Clay queries them in sequence until one returns a match, paying only for hits. Vendors and their agencies claim this lifts coverage from 50 to 70 percent to 85 to 95.
Alongside it sits Claygent, an AI agent that runs a written prompt down a column and answers questions no provider has a field for. Does this company have a sales team in Europe? Did it just publish a security page? Score this account from 1 to 100 and give the reasoning.
Restructuring Rev Ops
The operational change is that leads come from queries rather than static databases.
Under the old stack a company bought a list, loaded it, and scored it against fields that were accurate on the day of purchase. Contact data decays at roughly 2 percent a month, so a list enriched once is materially wrong within a year. Scoring lived in the CRM. Routing lived in the CRM. The list was a static artifact pretending to be current.
Clay inverts that. The account object stays in Salesforce, and the CRM remains the system of record. But enrichment, scoring and routing move into a live table that refreshes on a schedule, and the CRM becomes where the answers land rather than where they are computed.
The Catch
Clay repriced in March 2026 into two meters, data credits for lookups and actions for workflow steps, where a ten-step workflow charges ten actions. Point a wide table at an untriaged database and a month’s budget is gone in a week.
The product also needs an operator. The GTM engineer role exists because Clay does not run itself, and the people who are good at it think in systems rather than tasks. They are scarce and they are not cheap, which makes the license the smaller half of the cost. For a team running manual outbound to fifty accounts, this is overkill and the spreadsheet was fine.
The Catalyst Take: Cool Product, but Does It Have a Moat?
Clay is the Issue #2 headless thesis arriving on top of Salesforce. The system of record keeps the records but loses the work. The work moves to the orchestration layer and the agent running on top of it. Whether the value follows the work is a separate question, and the market map below argues that it largely does not. We said in Issue #5 that application-layer companies would increasingly build the intelligence rather than rent it; Clay is the same move executed against the data layer instead of the model layer.
A caution on the asset itself. Clay buys its coverage from 150 providers it does not own, so the moat is limited to workflow and switching cost rather than proprietary data. At a rumored 36 times a run rate, that is a great deal to pay for a product any well-funded competitor can assemble.
At Catalyst we have started asking GTM-heavy targets a single diligence question: are you conducting lead enrichment and scoring inside the CRM or above it? The answer says a lot about how AI-forward an organization really is.
03 — MARKET MAP
Agentic Rev Ops
The products built to arm the rep have compounded. The products built to replace the rep have stalled or failed. The incumbents, watching both, have been buying the first kind.
The Data and Orchestration Layer
These products build the list and decide who is worth contacting. A human still sends the email.
- Clay. Covered above. Ranks 150 data providers, queries them in sequence until one returns a match, and runs AI research prompts down a column for anything no provider has a field for. The output is a current, scored list written back to the CRM.
- Unify. Starts from the signal rather than the list. It watches for website visits, job changes and research behavior, identifies the company behind them, and turns that into a sequence while the interest is still live. Where Clay answers who fits, Unify answers who is in motion right now.
- Common Room. Pulls scattered traces of the same person across product usage, community, social and email into one identity, so a GitHub commenter and a trial signup resolve to a single account. Zoom bought it in July 2026 for $266.8 million in cash, which is the clearest price anyone has put on this tier.
The Autonomous SDR
These products do the whole job. They pick the target, write the message, send it, handle the reply and book the meeting. The pitch was a headcount line rather than a software line.
- 11x. Sells a named digital worker that runs the full outbound motion without a rep. It became the category’s cautionary tale: TechCrunch reported former employees saying contracts with break clauses had been counted as revenue, and ZoomInfo ended a trial after concluding the agent performed worse than its own human SDRs.
- Artisan. Same model, paired with its own contact database and a deliberately provocative campaign about not hiring humans. It disclosed roughly $7 million in ARR at the end of 2025, which was all it had to show after two years of the loudest marketing in software.
The category-level evidence is no better. BCG found in October 2026 that only 14 percent of sales leaders could point to measurable conversion improvements from AI agents, and that only 6 percent had reached genuinely autonomous end-to-end workflows.
The Incumbents
Each of the three has bought into the first tier rather than the second.
- Salesforce. Acquired Qualified around April 2026 and folded it into Agentforce, adding an agent that engages inbound visitors on the website before a rep sees them. This is the second time Salesforce has bought its way to agentic parity rather than building it, after Fin.
- HubSpot. Agreed in June 2026 to acquire Warmly, which identifies the individual person behind an anonymous website visit and routes them while the visit is still happening. Warmly was small, roughly $8 million in ARR across about 223 customers, so HubSpot was buying a product tuck-in rather than a business.
- ZoomInfo. The contact database that the first tier was built to route around. It bought DoubleO.ai in September 2026 and has begun moving customers off seat pricing toward purchased credits, which is the same usage meter the newer tools run on. Its market capitalization is roughly $3.5 billion against a 2021 peak above $25 billion.
The Catalyst Take: Keep Experimenting in Agentic Rev Ops
The dividing line in this category is not model quality or data coverage. It is whether the product hands a human a better input or tries to be the human.
So far human-in-the-loop / labor augmentation products are more effective. Human replacement models in sales (the ultimate human skill) have not shown themselves to work well enough (yet). That is why the exits are happening in the first tier and the embarrassments are in the second.
We said in Issue #5 that customer service consolidated early because it was one of the most obvious use cases for a language model. The rev ops sector is consolidating now, and the incumbents are buying agents that engage in identity resolution, signal detection and enrichment. We would be careful about reading that as a durable advantage.
Data in this category decays quickly, which will make the switching costs low at every layer, the CRM included. That results in a competitive market rather than a defensible one. The tools keep getting better, the incumbents occasionally overpay for a capability they could have built, and most of the value created will likely go to the customer rather than to anyone in the tech stack.
We like using these products considerably more than we like investing in them at current valuations.
Sources: Ballotpedia via Polialert (November 6, 2026), American Legislative Exchange Council (November 5, 2026), Data Center Watch / 10a Labs via Renewable Energy World (November 6, 2026), Fortune (November 4, 2026), MultiState, TokenPost (November 7, 2026), Associated Press (July 14, 2026), Federal Reserve Bank of Dallas (March 5, 2026), SemiAnalysis, JPMorgan and UBS via Seoul Economic Daily (November 7, 2026), Nomura via Superpower Daily (November 5, 2026), NOTUS via Spotlight PA (September 1, 2026).
Multiples.vc and SaaSRise on the Series D; Okara and ARR Club on revenue and customer counts; Clay (vendor) and RevPartners on product mechanics; Ziel Lab on implementation and the March 2026 repricing; Miniloop on setup burden. Clay is private, and every figure here reaches us through an aggregator relaying Reuters, the New York Times or Sacra rather than a primary outlet. The $200 million is a company expectation for the current quarter, not a reported result, and the coverage percentages are vendor marketing.
Zoom 10-Q via GTMLens on the Common Room price; RyWalker on Salesforce and Qualified; Industry Lens on HubSpot and Warmly; GTMLens on ZoomInfo; TechCrunch via New Market Pitch on 11x; New Market Pitch on Artisan; BCG via New Market Pitch (October 2026). Outside the Common Room price and the BCG survey, these figures come from category trackers rather than primary reporting, and private revenue figures are estimates unless disclosed. We have left out the widely repeated 11x churn statistic because we could not find a source for it. None of the three incumbent acquisitions disclosed a price.
This newsletter is for informational purposes only and does not constitute investment advice or an offer to sell or a solicitation to buy any security.
Forward to a founder, operator, or investor who is navigating AI adoption.
ir@catalyst.com
261 5th Ave
Suite 1102
New York NY 10016